October 2026 VFACTS figures reveal a rapidly changing Australian automotive market, with record new vehicle sales, accelerating Chinese brand growth and electric vehicles outselling petrol-powered cars.
Australia recorded 107,493 new vehicle deliveries during October 2026, representing a 6.8% year-on-year increase when VFACTS and Electric Vehicle Council figures are combined.
The initial VFACTS report recorded 103,325 deliveries, up 3.8%, before the additional electric vehicle registrations were included.
The results highlight the growing influence of Chinese automotive manufacturers, changing consumer preferences and increasing competition across Australia’s dealership networks.
October 2026 VFACTS: Toyota Leads as BYD Surges
Toyota maintained its position as Australia’s leading automotive brand, recording 20,649 deliveries, up 4.7% year-on-year.
However, BYD continued its remarkable expansion, delivering 10,025 vehicles, an increase of 153.2% compared with October 2025.
BYD has now occupied second place in the monthly brand rankings every month since April, highlighting the pace at which Chinese manufacturers are gaining ground.
Several established manufacturers experienced significant declines, while newer entrants continued increasing their Australian market presence.
Australia’s Top 10 Automotive Brands — October 2026
| Rank | Brand | Sales | Year-on-year |
|---|---|---|---|
| 1 | Toyota | 20,649 | +4.7% |
| 2 | BYD | 10,025 | +153.2% |
| 3 | Ford | 7,310 | -3.4% |
| 4 | Kia | 5,801 | -12.2% |
| 5 | Mazda | 5,730 | -19.7% |
| 6 | MG | 4,676 | +31.5% |
| 7 | Hyundai | 4,571 | -28.6% |
| 8 | GWM | 4,417 | -0.3% |
| 9 | Geely | 4,365 | +520.0% |
| 10 | Chery | 4,317 | +21.6% |
Five Chinese automotive brands now occupy positions in Australia’s top 10, reflecting a substantial shift in the competitive landscape.
Elsewhere, Tesla recorded 4,050 deliveries, up 342.1%, while Zeekr achieved 1,874 deliveries, an increase of 767.6%.
Traditional manufacturers including Mitsubishi (-50.0%), Subaru (-41.5%) and Volkswagen (-46.4%) experienced particularly difficult months.
October 2026 VFACTS: EVs Overtake Petrol
One of October’s most significant developments was the changing balance between vehicle powertrains.
After electric vehicles led the market for two consecutive months, diesel returned to first place in October.
October 2026 sales by fuel type:
| Fuel type | Deliveries | Market share |
|---|---|---|
| Diesel | 25,649 | 23.9% |
| Electric | 24,845 | 23.1% |
| Petrol | 23,605 | 22.0% |
| Hybrid | 18,434 | 17.1% |
| Plug-in hybrid | 11,745 | 10.9% |
Figures exclude heavy commercial vehicles.
Electric vehicles nevertheless outsold conventional petrol-powered vehicles during October, continuing a recent change in the Australian market.
Despite diesel returning to the monthly lead, diesel sales were down 14.7% year-on-year.
For the first 10 months of 2026, petrol remains the leading individual fuel type with 27.5% market share, followed by diesel at 24.3% and electric vehicles at 19.3%.
Toyota HiLux Returns to Number One
The Toyota HiLux reclaimed the title of Australia’s best-selling vehicle in October, recording 5,954 deliveries, ahead of the Ford Ranger on 4,841.
The Ranger remains narrowly ahead in the year-to-date standings, with 42,699 deliveries, just 129 more than the HiLux.
The Toyota RAV4 finished third, followed by the Tesla Model Y and BYD Sealion 7.
Australia’s Top 10 Selling Models — October 2026
| Rank | Model | Sales |
|---|---|---|
| 1 | Toyota HiLux | 5,954 |
| 2 | Ford Ranger | 4,841 |
| 3 | Toyota RAV4 | 4,718 |
| 4 | Tesla Model Y | 3,105 |
| 5 | BYD Sealion 7 | 2,524 |
| 6 | Toyota Prado | 2,397 |
| 7 | Chery Tiggo 4 | 2,178 |
| 8 | BYD Atto 2 | 1,943 |
| 9 | BYD Shark 6 | 1,843 |
| 10 | Geely EX5 | 1,789 |
Five of the top 10 selling models now come from Chinese automotive brands, including three BYD models.
The Ford Everest narrowly missed the top 10, finishing eleventh with 1,741 deliveries.
Chinese-Built Vehicles More Than Double
Perhaps the clearest indication of Australia’s changing automotive market comes from vehicle manufacturing origins.
China accounted for 41,671 new vehicle deliveries in October, an increase of 104.2% compared with October 2025.
This represents approximately 38.8% of Australia’s total new vehicle market for the month.
By comparison:
- Japan: 24,089 deliveries, down 13.1%
- Thailand: 18,505 deliveries, down 11.1%
- South Korea: 9,531 deliveries, down 23.5%
- Germany: 3,745 deliveries, down 24.0%
These figures reflect vehicle manufacturing locations rather than brand ownership. Chinese-built vehicles include models sold by manufacturers headquartered outside China.
Nevertheless, the results demonstrate the increasing importance of Chinese automotive manufacturing to the Australian market.
The growing international ambitions of Chinese manufacturers are also evident in their overseas sales performance, with Geely, BYD and Chery reporting substantial export growth during October 2026.
SUVs Continue to Dominate
SUVs represented 62.6% of total new vehicle sales during October, maintaining their substantial lead over other vehicle categories.
Light commercial vehicles accounted for 20.0%, passenger vehicles 14.4% and heavy commercial vehicles 3.0%.
Medium SUVs continued to experience strong growth, recording 31,970 deliveries, up 23.8% year-on-year.
Small SUV sales also increased 12.1%, while large SUVs declined 17.9%.
The continued popularity of SUVs, combined with the rapid expansion of electric and Chinese-manufactured models, is creating an increasingly competitive environment across several of Australia’s largest vehicle segments.
What October 2026 VFACTS Means for Australian Dealerships
October’s figures highlight a market undergoing significant structural change.
While overall new vehicle sales remain strong, growth is increasingly concentrated among manufacturers expanding their product ranges, introducing new technologies and challenging established brands.
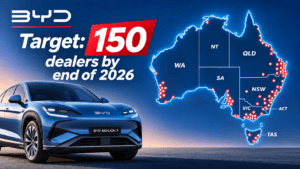
The growth of BYD, Geely, Chery and other emerging manufacturers is changing Australia’s dealership landscape, bringing new competitors into established sales territories and creating additional demand for experienced automotive management, sales, technical and aftersales personnel.
At the same time, the substantial sales declines recorded by several established manufacturers highlight the pressure facing traditional dealership networks.
For dealership operators, distributors and automotive professionals, the changing market presents both opportunities and challenges.
Australia is buying more new vehicles, but where those vehicles come from, how they are powered and which brands customers choose are changing rapidly.
The October 2026 results provide some of the clearest evidence yet of that transformation.
Source: October 2026 VFACTS data and Electric Vehicle Council figures, as reported by CarExpert. Sales figures represent reported new vehicle deliveries. Some datasets exclude heavy commercial vehicles or certain manufacturers, as indicated.